
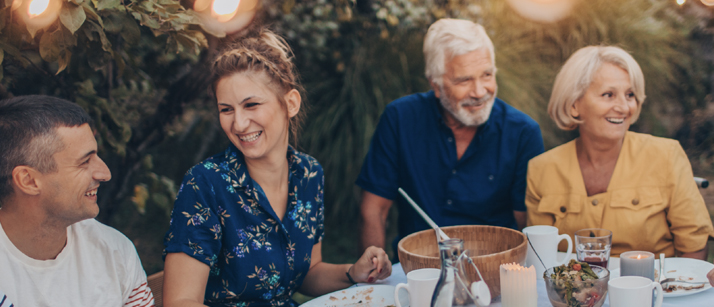


Two in five (42%) of parents are paying for their adult children to join their multigenerational holidays, with three in ten (29%) planning to always do so, according to new research released today from Kent Reliance.
Parents who fork out for their adult children pay £2,423.90 in total on average for a trip. In addition to paying for flights and accommodation, parents are footing the bill for meals out (57%), groceries (42%) and activities (33%) while they are away.
According to the poll of 4,000 UK adults, nearly a third (29%) have been on a multigenerational holiday in the last three years, and one in five (20%) plan to take one in the next three years.
Quality time together (62%) and the chance to create cherished memories (47%) are the key motivators for all multigenerational holidaymakers. For Gen Z, there is also recognition that they get to visit better holiday destinations (25%). The majority (60%) of multigenerational holiday goers say they are the holidays they look forward to most.
When it comes to funding the cost, nearly half (48%) of parents to adult children had ready access to the money needed to pay for their last multigenerational holiday.
Meanwhile, 37% of respondents saved to pay for their multigenerational holiday, and of those more than a third (39%) used their current account.
Louise Halliwell, Group Savings Director, Kent Reliance, comments:
“Spending time with family is one of life’s greatest pleasures and it is wonderful to see just how many people are enjoying coming together whether in the UK or abroad. For parents of grown-up children, the quality time comes at a financial cost but one many tell us they are happy to bear.
While many respondents were fortunate enough to have a holiday nest egg to fund their holidays, for others it is a matter of saving over time to ensure they can make the most of the time they have together.
Whether saving for a short or a long time, for a small or a bigger amount, I'd always recommend people shop around and ensure they are getting a good interest rate on their savings as it can make a real difference. By setting a clear and manageable savings goal, people could earn themselves the equivalent of a meal out or an activity while away.”
Share this article
Related news
Lifestyle
21 Oct 2026
What to consider before choosing a fixed-rate bond?

Product Team
21 Oct 2026
What to consider before choosing a fixed-rate bond?
Product Team
Fixed-rate bonds offer the benefit of consistent interest rates, though they also lock withdrawal access for the duration of their agreed term. As a result, it can be helpful to consider your future financial plans to ensure you pick the term length that best aligns with when you’ll next need access to your savings.
Read more
Lifestyle
15 Oct 2026
Can you have an ISA and a savings account at the same time?
Product Team
15 Oct 2026
Can you have an ISA and a savings account at the same time?
Product Team
You can hold both an ISA and savings account at the same time, however it’s helpful to know the positives and challenges of both types of account. The interest you earn in an ISA is 100% tax-free*, however, you’re currently limited to only £20,000 of annual ISA deposits. Standard savings accounts can still earn you tax-free interest, subject to your PSA, and are generally unburdened by an annual deposit limit.
Read more